What Form 8842 is
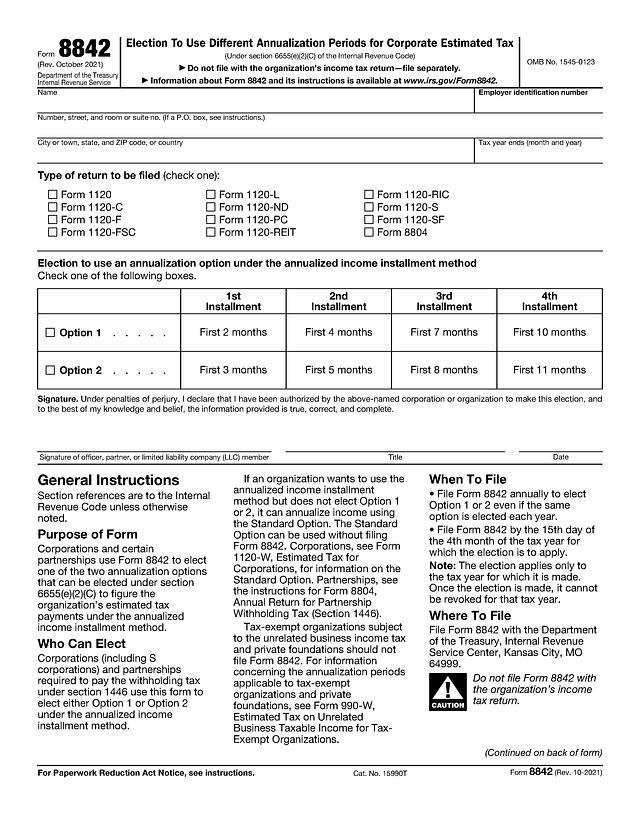
Form 8842, Election To Use Different Annualization Periods for Corporate Estimated Tax, lets a corporation or certain partnerships choose one of two alternative annualization periods under Internal Revenue Code section 6655(e)(2)(C). The choice affects how estimated tax installments are figured under the annualized income installment method. This template is the Rev. October 2021 edition, a 2-page PDF with the form and general instructions on page 1 and the rest of the instructions on page 2. As of October 3, 2026, it is still the current version on the IRS Form 8842 page.
Under the annualized income installment method, each estimated payment is based on income earned during the months before it is due, instead of four equal payments. The law provides a standard set of periods that needs no election. Form 8842 is only needed if the organization wants Option 1 or Option 2 instead.
The two options on the form
| Installment | Option 1 | Option 2 |
|---|---|---|
| 1st | First 2 months | First 3 months |
| 2nd | First 4 months | First 5 months |
| 3rd | First 7 months | First 8 months |
| 4th | First 10 months | First 11 months |
Which option, if any, suits an organization depends on when it earns its income during the year. That decision belongs with the company's tax adviser. The form still points corporations to Form 1120-W for the standard option, but the IRS has since made Form 1120-W historical. Corporate estimated tax guidance now lives in Publication 542 and the Form 1120 instructions. Partnerships should see the Form 8804 instructions.
Who uses it
According to the form, these organizations can make the election:
- Corporations, including S corporations, filing returns in the Form 1120 series.
- Partnerships required to pay withholding tax under section 1446, which file Form 8804.
Tax-exempt organizations subject to unrelated business income tax, and private foundations, should not file Form 8842. Their annualization periods are covered by Form 990-W.
What to have ready
- The organization's legal name and employer identification number (EIN).
- Its mailing address.
- The month and year its tax year ends.
- The return it will file for that year.
- The option it has decided to elect, and an authorized officer, partner, or LLC member to sign.
How to fill out Form 8842 online
Click "Fill Template Now," type into the fields, sign, and download the completed election to print and mail.
Identification
Enter the organization's name, EIN, street address with room or suite number, and city or town, state, and ZIP code (or country). Use a P.O. box only if the post office doesn't deliver to the street address. If mail goes to a third party such as an accountant, write "C/O" with their name and address on the street line. Then enter the month and year the tax year ends.
Type of return to be filed
Check one box: Form 1120, 1120-C, 1120-F, 1120-FSC, 1120-L, 1120-ND, 1120-PC, 1120-REIT, 1120-RIC, 1120-S, 1120-SF, or 8804.
Election
Check either the Option 1 or the Option 2 box. Check only one.
Signature
The signer declares, under penalties of perjury, that they are authorized to make the election. For a corporation, that is the president, vice president, treasurer, assistant treasurer, chief accounting officer, or another authorized officer such as a tax officer. For a partnership, a partner or LLC member signs. A receiver, trustee, or assignee signs instead when filing for the organization, and a bankruptcy receiver or trustee must attach the court order authorizing the signature. Add the title and date.
When and where to file
- Deadline: by the 15th day of the 4th month of the tax year the election applies to. For a calendar-year corporation, that is April 15.
- Every year: file a new Form 8842 each year you want Option 1 or 2, even if you choose the same option again.
- No revoking: the election applies only to that tax year and can't be revoked for that year once made.
- Where: Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999. Mail it separately. Do not attach it to the income tax return.
Because Form 8842 is mailed on paper, check the IRS e-signature rules in IRM 10.10.1 before signing electronically. If in doubt, print it and have the officer sign in ink.
Common mistakes
- Filing after the 15th day of the 4th month, which is too late for that year.
- Assuming last year's election carries over.
- Attaching the form to Form 1120 instead of mailing it separately.
- Checking both options, or none.
- Filing it for a tax-exempt organization or private foundation, which should use Form 990-W instead.
Find related forms in our IRS tax form templates.