What the form is
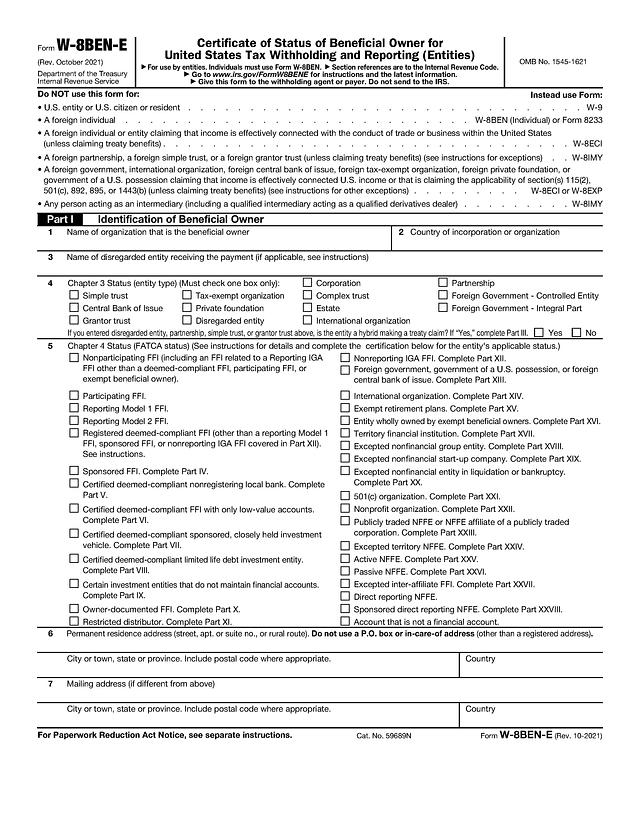
Form W-8BEN-E, Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities), is how a foreign company or other non-US entity tells a US payer who it is and what its tax status is. The payer, called the withholding agent, uses the form to decide which withholding rate applies to US-source payments, and to identify the entity's FATCA status. You give the form to the payer. You do not send it to the IRS. The edition on the IRS site is Rev. October 2021 and runs to eight pages. The IRS publishes Instructions for Form W-8BEN-E, which you should keep open while filling in the form.
The form says on page 1 that it is for entities only. Individuals use Form W-8BEN, which has its own how-to guide.
Who typically needs it
A foreign company, partnership, trust, foundation or other entity that receives US-source income, or holds an account with a US broker or foreign financial institution, is usually asked for this form. Typical requesters are US customers paying a foreign supplier, platforms and marketplaces, banks and brokers opening an entity account. The list at the top of page 1 shows when another form is needed instead: W-9 for US entities, W-8ECI for income connected with a US trade or business, and W-8IMY for intermediaries. Which status applies to your entity is a question for a tax adviser or the withholding agent. This page covers how to complete the form.
What you need before you start
- The entity's legal name, country of incorporation and permanent residence address (no P.O. box).
- The entity type for chapter 3 purposes and the FATCA (chapter 4) status. The payer often tells you which one it expects.
- The US taxpayer identification number if one is required, the foreign tax identifying number, and the GIIN if the entity has one.
- For a treaty claim, the treaty country, article, withholding rate and type of income.
- The name and capacity of the person who signs for the entity.
How to fill it out online with PDF Editify
Open this page and click Fill Template Now. The form opens in the editor with its fields ready to type into. Opening it does not need a card, but downloading the completed PDF needs a plan: One Week Plan at $3 one-time, Standard at $10 per month or $100 per year, or Lifetime from $99 one-time.
Part I, Identification of Beneficial Owner
- Line 1 and 2: the organization name and its country of incorporation or organization.
- Line 3: the name of a disregarded entity receiving the payment, if applicable.
- Line 4, Chapter 3 Status: tick exactly one entity type, such as corporation, partnership or trust. Answer the hybrid entity question below it if it applies.
- Line 5, Chapter 4 Status: tick the FATCA status that applies. Many statuses point to a later part you must complete, for example Part XXV for an active NFFE or Part XXVI for a passive NFFE.
- Lines 6 and 7: permanent residence address and, if different, a mailing address.
- Lines 8 to 10: the US TIN if required, the GIIN, the foreign TIN (or the box if not legally required), and any reference numbers.
Parts II and III
Part II is only for a disregarded entity with a GIIN or a branch of an FFI outside its country of residence. Part III is the treaty claim, for chapter 3 purposes only. Line 14 certifications cover the country of residence and limitation on benefits, and line 15 holds special rates and conditions, with the article, paragraph, rate and type of income.
Parts IV to XXVIII
Complete only the part that matches the status you ticked on line 5. Leave the others blank. Each part contains its own certification lines, numbered 16 to 43.
Part XXIX and Part XXX
Part XXIX asks for the name, address and TIN of each substantial US owner, and is used by a passive NFFE. Part XXX is the certification: signature of the individual authorized to sign, their printed name and the date in MM-DD-YYYY format.
Signing, and where and how to submit
The signer certifies under penalties of perjury, including having the capacity to sign for the entity. In PDF Editify you can draw, type or upload a signature. See sign a PDF for how that works. Then download the PDF and give it to the withholding agent in the way it requests, which may be an upload portal or email. Do not send it to the IRS.
Deadlines and fees
| Item | What the IRS says |
|---|---|
| When to provide it | Before income is paid or credited to you. Failing to provide it when requested may lead to withholding at a 30% rate or backup withholding in certain cases. |
| Validity | Generally from the date signed to the last day of the third succeeding calendar year, unless a change in circumstances makes information incorrect. |
| Change in circumstances | Notify the withholding agent within 30 days. |
| Fee | The IRS charges no fee because the form is not filed with it. |
Source: IRS Instructions for Form W-8BEN-E, checked on 2 November 2026.
Common mistakes
- Using this form for an individual, who needs Form W-8BEN.
- Ticking more than one box on line 4, which allows exactly one.
- Choosing a FATCA status and skipping the part it refers to.
- Using a P.O. box as the permanent residence address.
- Sending the form to the IRS instead of the payer.
- Continuing to use an old form after your circumstances changed.